Daily Trade Setups: Trading US CPI
MACRO, CPI PREVIEW & DERIVATIVES DESK BRIEFING
THE TAKE: CPI CATALYST TESTS HAWKISH FED PRICING AND 7,810 GAMMA PIVOT
As markets approach the US September CPI release—sitting just two weeks ahead of the upcoming FOMC rate decision—a hawkish shift has re-emerged across front-end rate curves. Market-implied odds for a 25 bps rate hike have rebounded to 24% (up from post-NFP lows), driven by persistent energy price strength (motor fuel prices projected +9.6% MoM).
Wall Street consensus models expect Headline CPI to accelerate to +0.57% MoM (the highest monthly reading since April during the initial Middle East supply shock), bringing Headline CPI YoY to +3.6%. Conversely, Core CPI is expected to print softer at +0.16% MoM (+2.4% YoY). With official PCE readings scheduled for release the day after the Fed meeting, this CPI print serves as the primary inflation barometer for FOMC policy expectations.
CROSS-ASSET MACRO & YIELD CURVE DYNAMICS
Federal Reserve Fedspeak: NY Fed President John Williams backed one final 25 bps hike for 2026, while Richmond Fed President Thomas Barkin reiterated the necessity of maintaining a restrictive policy stance to anchor inflation expectations.
Yield Curve Flattening: Front-end Treasury yields nudged higher (US 2Y +2.1 bps to 4.78%), while risk-off demand flattened the long end (US 10Y -2.9 bps to 5.21%). European sovereign spreads remain wide, with the Franco-German 10Y spread holding at 137 bps.
Semiconductor & Data Center Stress: Semiconductor stocks extended their losing streak to 5 consecutive sessions (Philly Semiconductor Index -0.23%). AI data center issuers faced severe spread widening, with CoreWeave 5Y CDS expanding +79 bps to close near 1,000 bps intraday alongside weakness in Applied Digital (-3.48%).
SPX ACTIONABLE TRADING & GAMMA LEVEL PLAYBOOK
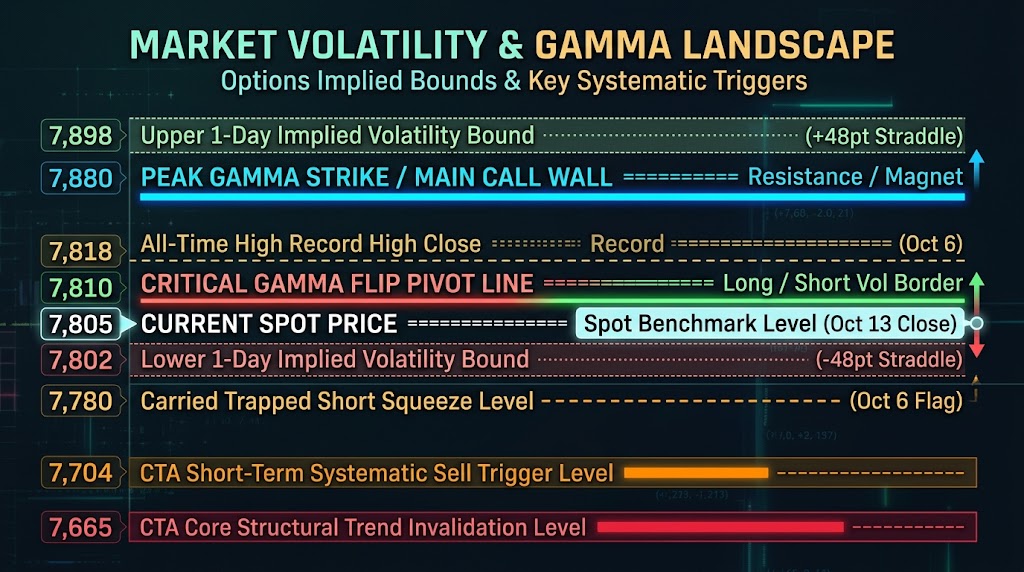
Derivatives positioning into Friday's options expiration prices a 48-point expected move in S&P 500 futures (ES), establishing an implied volatility corridor of 7,802 to 7,898.
1. Long Gamma Cushion Regime (Inside 7,810 – 7,880)
Market Structure: Options dealers remain net long gamma above 7,810, with the largest open-interest concentration anchored at the 7,880 strike.
Execution Strategy: Expect dealer hedging (buying dips, selling rallies) to dampen price action and suppress realized volatility. Fade directional breakouts toward the 7,880 strike or the 7,898 upper implied boundary, utilizing range-bound mean-reversion strategies.
2. Short Gamma Acceleration Regime (Breakdown Below 7,810)
Market Structure: A sustained 15-minute or 1-hour close below 7,810 flips dealer gamma to negative. Below this pivot, market makers must sell into falling markets to maintain delta neutrality.
Execution Strategy: Treat 7,810 as a strict line-in-the-sand invalidation level. A downside break of 7,810 validates short-gamma acceleration, opening tactical downside targets at 7,802 (lower 1-day straddle boundary) and structural support levels at 7,780 / 7,760.
Disclaimer: The material provided is for information purposes only and should not be considered as investment advice. The views, information, or opinions expressed in the text belong solely to the author, and not to the author’s employer, organization, committee or other group or individual or company.
Past performance is not indicative of future results.
High Risk Warning: CFDs are complex instruments and come with a high risk of losing money rapidly due to leverage. 68% and 74% of retail investor accounts lose money when trading CFDs with Tickmill UK Ltd and Tickmill Europe Ltd respectively. You should consider whether you understand how CFDs work and whether you can afford to take the high risk of losing your money.
Futures and Options: Trading futures and options on margin carries a high degree of risk and may result in losses exceeding your initial investment. These products are not suitable for all investors. Ensure you fully understand the risks and take appropriate care to manage your risk.
Patrick has been involved in the financial markets for well over a decade as a self-educated professional trader and money manager. Flitting between the roles of market commentator, analyst and mentor, Patrick has improved the technical skills and psychological stance of literally hundreds of traders – coaching them to become savvy market operators!